
Professional services firm Marsh (NYSE:MRSH) reported Q3 2026 results exceeding the market’s revenue expectations, with sales up 8.1% year on year to $6.86 billion. Its non-GAAP profit of $2.03 per share was 3.2% above analysts’ consensus estimates.
Is now the time to buy Marsh? Find out by accessing our full research report, it’s free.
Marsh (MRSH) Q3 2026 Highlights:
- Revenue: $6.86 billion vs analyst estimates of $6.64 billion (8.1% year-on-year growth, 3.4% beat)
- Adjusted EPS: $2.03 vs analyst estimates of $1.97 (3.2% beat)
- Operating Margin: 17.7%, in line with the same quarter last year
- Free Cash Flow Margin: 20.4%, down from 31.6% in the same quarter last year
- Organic Revenue rose 5% year on year (beat)
- Market Capitalization: $85.13 billion
Company Overview
With roots dating back to 1871 and a presence in over 130 countries, Marsh (NYSE:MRSH) is a global professional services firm that helps organizations manage risk, strategy, and workforce challenges through its four specialized businesses.
Revenue Growth
A company’s long-term sales performance is one signal of its overall quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years.
With $28.46 billion in revenue over the past 12 months, Marsh is a behemoth in the business services sector and benefits from economies of scale, giving it an edge in distribution. This also enables it to gain more leverage on its fixed costs than smaller competitors and the flexibility to offer lower prices.
As you can see below, Marsh’s 8.3% annualized revenue growth over the last five years was solid. This is an encouraging starting point for our analysis because it shows Marsh’s demand was higher than many business services companies.
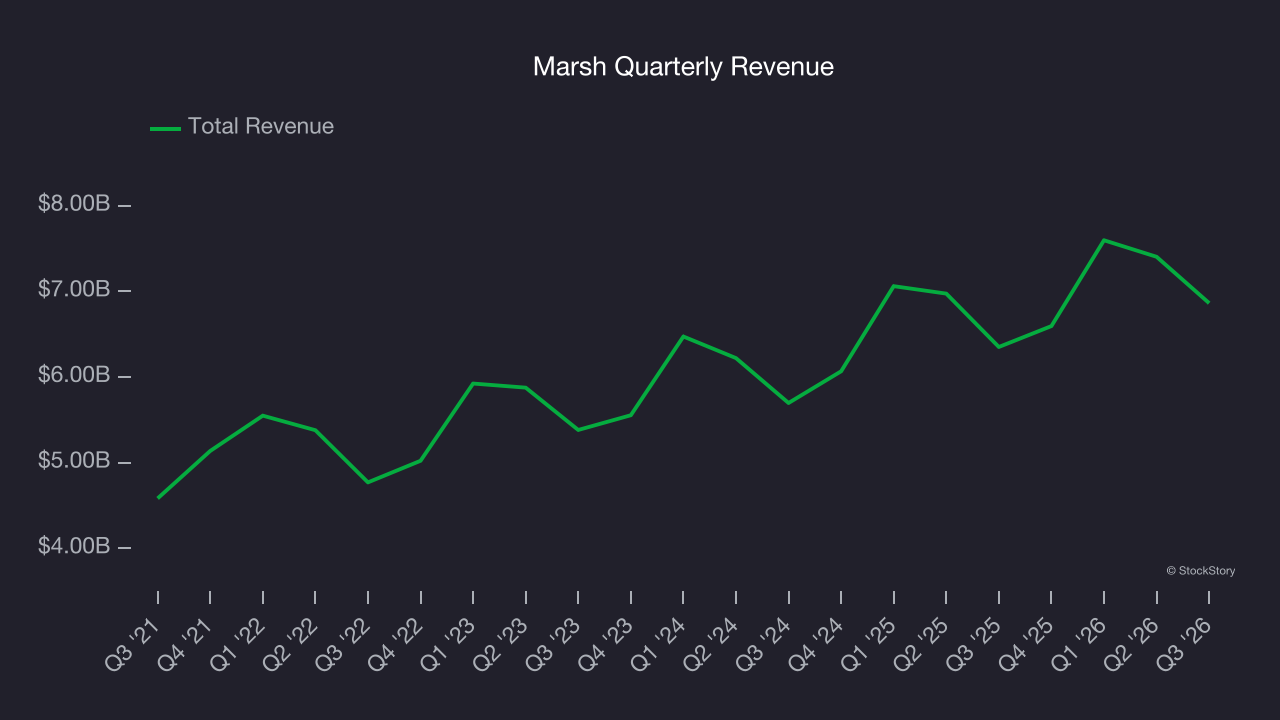
We at StockStory place the most emphasis on long-term growth, but within business services, a half-decade historical view may miss recent innovations or disruptive industry trends. Marsh’s annualized revenue growth of 9% over the last two years aligns with its five-year trend, suggesting its demand was predictably strong. 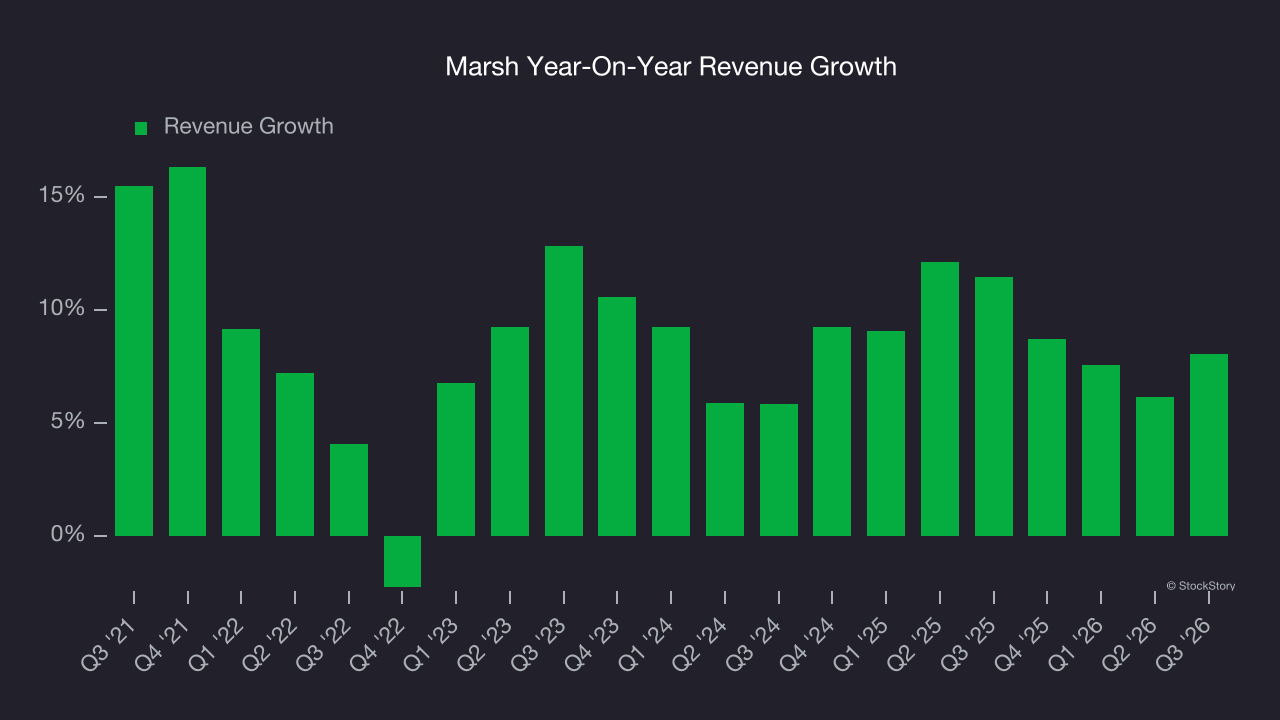
We can better understand the company’s sales dynamics by analyzing its organic revenue, which strips out one-time events like acquisitions and currency fluctuations that don’t accurately reflect its fundamentals. Over the last two years, Marsh’s organic revenue averaged 4.6% year-on-year growth. Because this number is lower than its two-year revenue growth, we can see that some mixture of acquisitions and foreign exchange rates boosted its headline results. 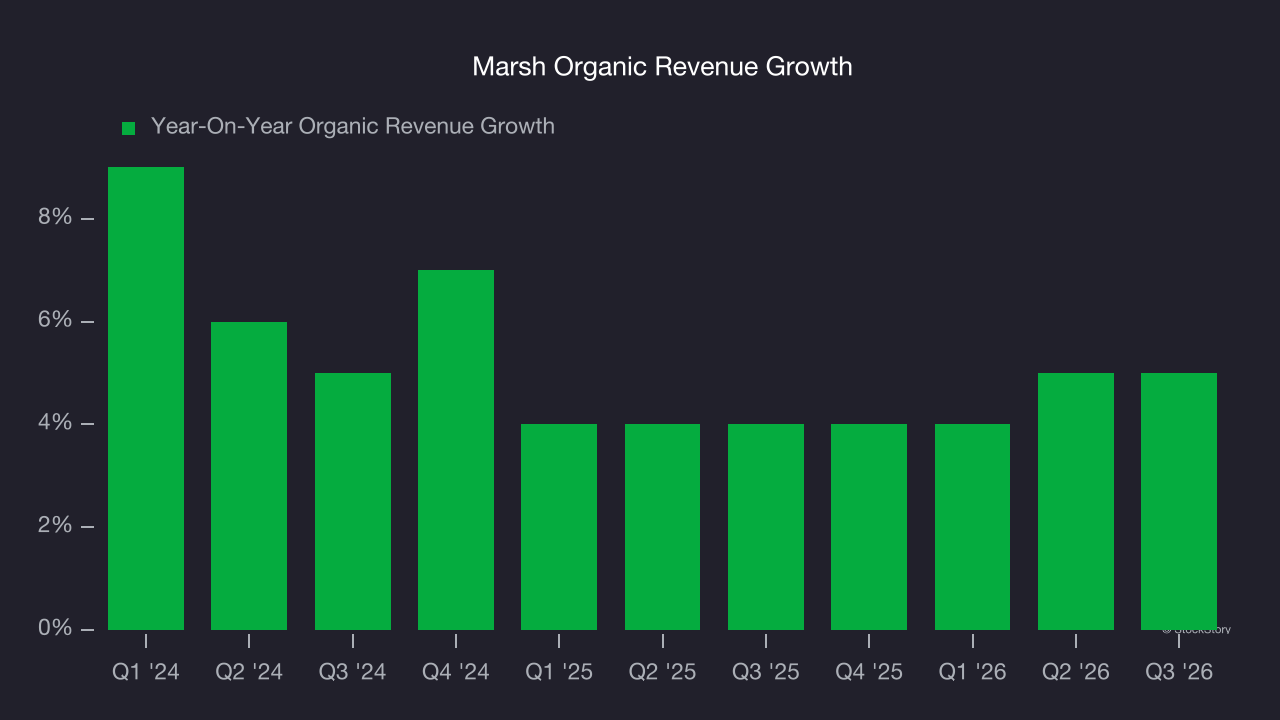
This quarter, Marsh reported year-on-year revenue growth of 8.1%, and its $6.86 billion of revenue exceeded Wall Street’s estimates by 3.4%.
Looking ahead, sell-side analysts expect revenue to grow 4% over the next 12 months, a deceleration versus the last two years. This projection is underwhelming and indicates its products and services will face some demand challenges. At least the company is tracking well in other measures of financial health.
ONE MORE THING: 3 Hidden Platforms Growing 3X Faster than Amazon, Google, and PayPal. Amazon, Google, and Meta all followed the same playbook: Dominate an ignored market. Build an unbeatable moat. Scale until you’re unstoppable.
These three platforms are running that exact playbook right now. The early investors in Amazon made fortunes. The early investors in these could do the same. Get All 3 Stocks Here for FREE.
Adjusted Operating Margin
Adjusted operating margin is one of the best measures of profitability because it tells us how much money a company takes home after subtracting all core expenses, like marketing and R&D. It also removes various one-time costs to paint a better picture of normalized profits.
Marsh has been a well-oiled machine over the last five years. It demonstrated elite profitability for a business services business, boasting an average adjusted operating margin of 26%.
Looking at the trend in its profitability, Marsh’s adjusted operating margin rose by 2.2 percentage points over the last five years, as its sales growth gave it operating leverage.
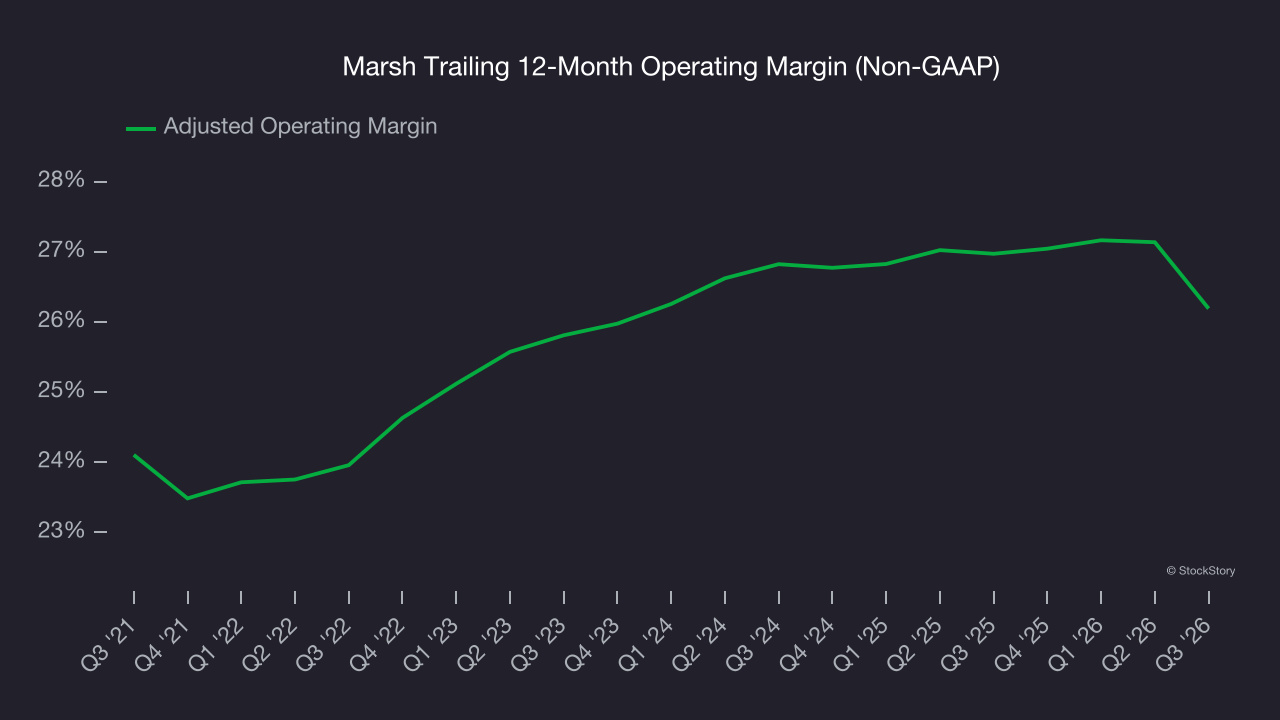
This quarter, Marsh generated an adjusted operating margin profit margin of 19.1%, down 3.6 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue.
Earnings Per Share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Marsh’s EPS grew at 11.6% compounded annual growth rate over the last five years, higher than its 8.3% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
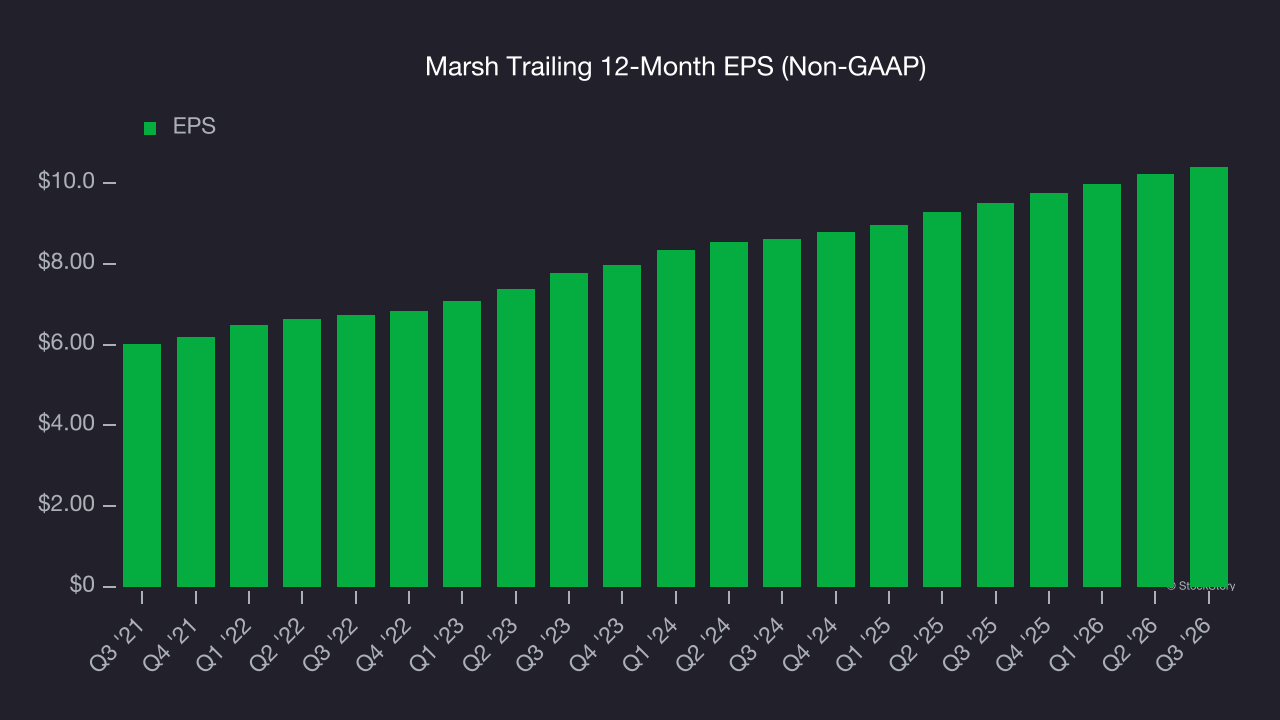
Diving into Marsh’s quality of earnings can give us a better understanding of its performance. As we mentioned earlier, Marsh’s adjusted operating margin declined this quarter but expanded by 2.2 percentage points over the last five years. Its share count also shrank by 6.6%, and these factors together are positive signs for shareholders because improving profitability and share buybacks turbocharge EPS growth relative to revenue growth. 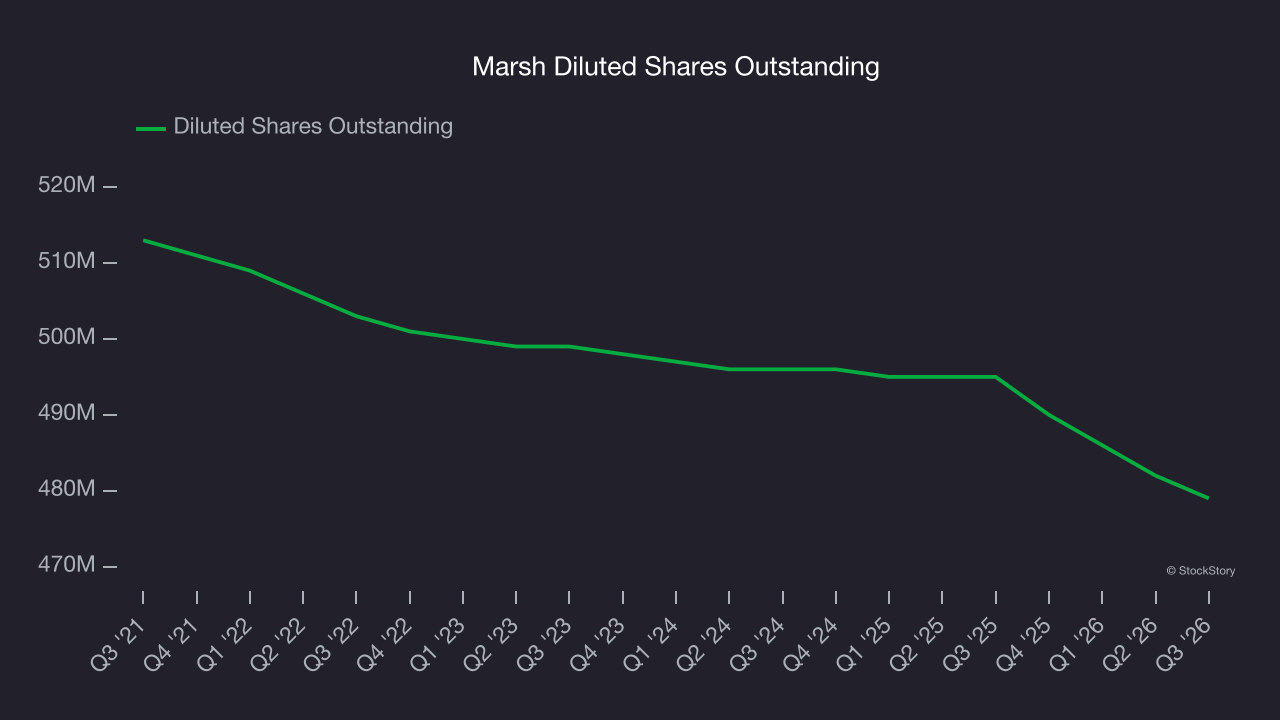
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For Marsh, its two-year annual EPS growth of 9.9% was lower than its five-year trend. This wasn’t great, but at least the company was successful in other measures of financial health.
In Q3, Marsh reported adjusted EPS of $2.03, up from $1.85 in the same quarter last year. This print beat analysts’ estimates by 3.2%. Over the next 12 months, Wall Street expects Marsh’s full-year EPS to grow 7.6% from $10.40 to $11.19.
Key Takeaways from Marsh’s Q3 Results
We enjoyed seeing Marsh beat analysts’ revenue expectations this quarter. We were also happy its organic revenue narrowly outperformed Wall Street’s estimates. Overall, we think this was a decent quarter with some key metrics above expectations. The stock traded up 2.9% to $183.65 immediately following the results.
Marsh had an encouraging quarter, but one earnings result doesn’t necessarily make the stock a buy. Let’s see if this is a good investment. When making that decision, it’s important to consider its valuation, business qualities, as well as what has happened in the latest quarter. We cover that in our actionable full research report which you can read here (it’s free).